
AI x Management Incentive Plans: Is Private Equity Keeping Pace?
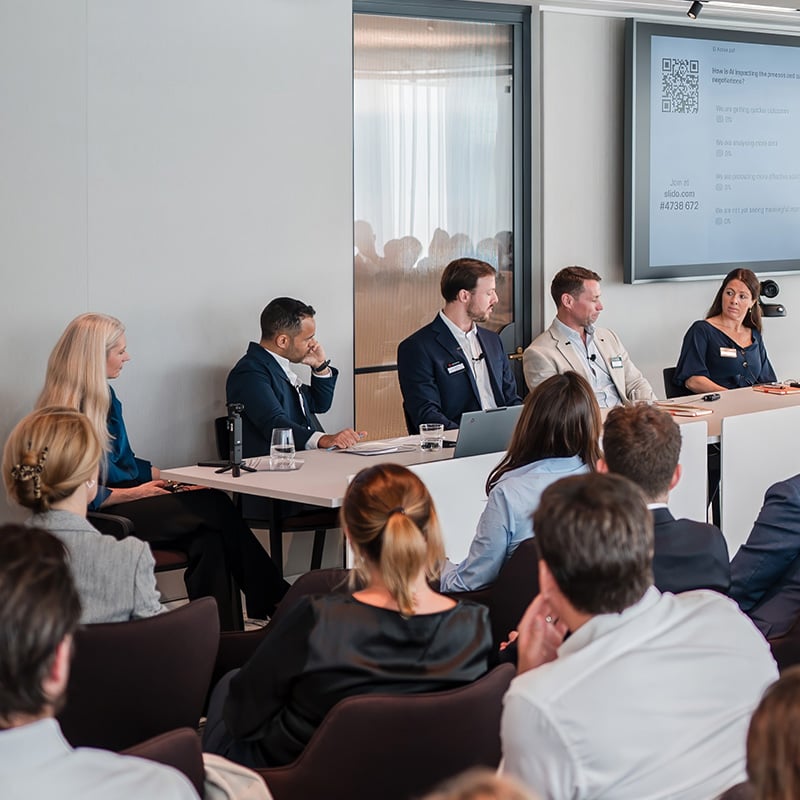
On 22 September, Goodwin UK partners Carl Bradshaw and Anna Humphrey were joined by Armon Bättig of Ledgy, Emma Halton of PwC, and David Kirkpatrick of Jamieson Corporate Finance for a discussion on what the rise of AI means for management incentive plans (MIPs) in practice. The conversation explored how AI is changing value-creation strategies, valuations, plan design, implementation, and management — and what investors and portfolio company leaders should be thinking about now.
For private equity, the question is no longer whether AI will affect portfolio companies but how quickly its impact will become visible in performance, talent strategy, and incentive design. While the market is still in the early stages of translating AI adoption into management equity structures, several themes are already emerging.
Five Key Takeaways
1. The talent war has entered a new phase, but MIP adaptation is not a given.
A tax-efficient MIP could once help lure strong managers away from the corporate world. AI engineers and transformation leads are commanding significant premiums, and private equity has its work cut out to sustain competitive packages for this specialist talent. Previous waves of technology disruption have changed business models, the people required to deliver strategy, and the way value is created, without necessarily transforming MIP models. The question now is whether AI will reach incentive plans more profoundly — not only through top-ups or resets to existing incentives but potentially through more fundamental reconfiguration of new MIPs.
2. Measurement does not automatically mean returns.
AI adoption is not necessarily a proxy for value. Businesses are using AI unevenly across functions, and productivity or cost-efficiency gains may be outweighed by infrastructure investment, implementation costs, and token usage. One of the design failures private equity most often identifies in hindsight is setting targets too high relative to what management can realistically control — precisely the risk that poorly specified AI targets may create. If a metric cannot be reliably assessed, genuinely influenced by management, and connected to sponsor returns, it may not belong in the MIP. At the same time, every available lever needs to be considered where AI is central to business transformation.
3. Early attempts at alignment are modest and varied.
Early market practice remains limited. Only a small proportion of plans have reportedly incorporated an AI component, ranging from explicit AI metrics to broader business transformation goals and qualitative KPIs. Most companies making meaningful AI investments have not yet reflected that spend in their long-term reward structures. Where changes are emerging, they include larger awards for key AI talent, equity vesting criteria linked to AI objectives — not dissimilar to ESG-linked incentives — and leaver provisions that allow some earned equity to be retained as a way to attract talent and manage behavioral risk from departed managers.
4. Data, diligence, and plan management advances.
AI is improving data storage and accessibility while enabling faster benchmarking, financial modelling, and first drafts of advisory materials. Over time, this may shift adviser support towards higher-value context, judgement, and relationship-led contributions. MIP platforms are also incorporating AI into product innovation, while investors and regulatory authorities are using technology in areas such as tax analysis and legislative compliance.
5. Other forces at work.
AI disruption is not operating in isolation. MIP design and negotiation is navigating longer hold periods, innovative liquidity solutions, potential tax reforms, and the continuing challenge of aligning incentives across jurisdictions. The immediate task is not to redesign incentive plans around AI out of fear. It is to identify where AI is already influencing performance, assess whether existing metrics reflect that shift, and ensure incentive structures remain strategic rather than reactive. For sponsors and management teams, the priority should be disciplined evaluation: Where AI changes value creation, MIPs may need to evolve; where it does not, incentives should continue to reward the fundamentals that drive returns.
Goodwin’s global Private Equity group advises private equity sponsors, portfolio companies, and management teams on management equity and executive compensation across borders, as well as every other aspect of the full investment lifecycle. Please get in touch to discuss how we can support you.
This informational piece, which may be considered advertising under the ethical rules of certain jurisdictions, is provided on the understanding that it does not constitute the rendering of legal advice or other professional advice by Goodwin or its lawyers. Prior results do not guarantee similar outcomes.
Contacts
- Carl Bradshaw

Carl Bradshaw
Partner - Anna Humphrey

Anna Humphrey
Partner